Financing a Modular Home in Ireland: What Banks Look For
What Irish banks actually look for when financing a modular home — certification, contracts, foundations, stage payments and how to make your build lender-ready.
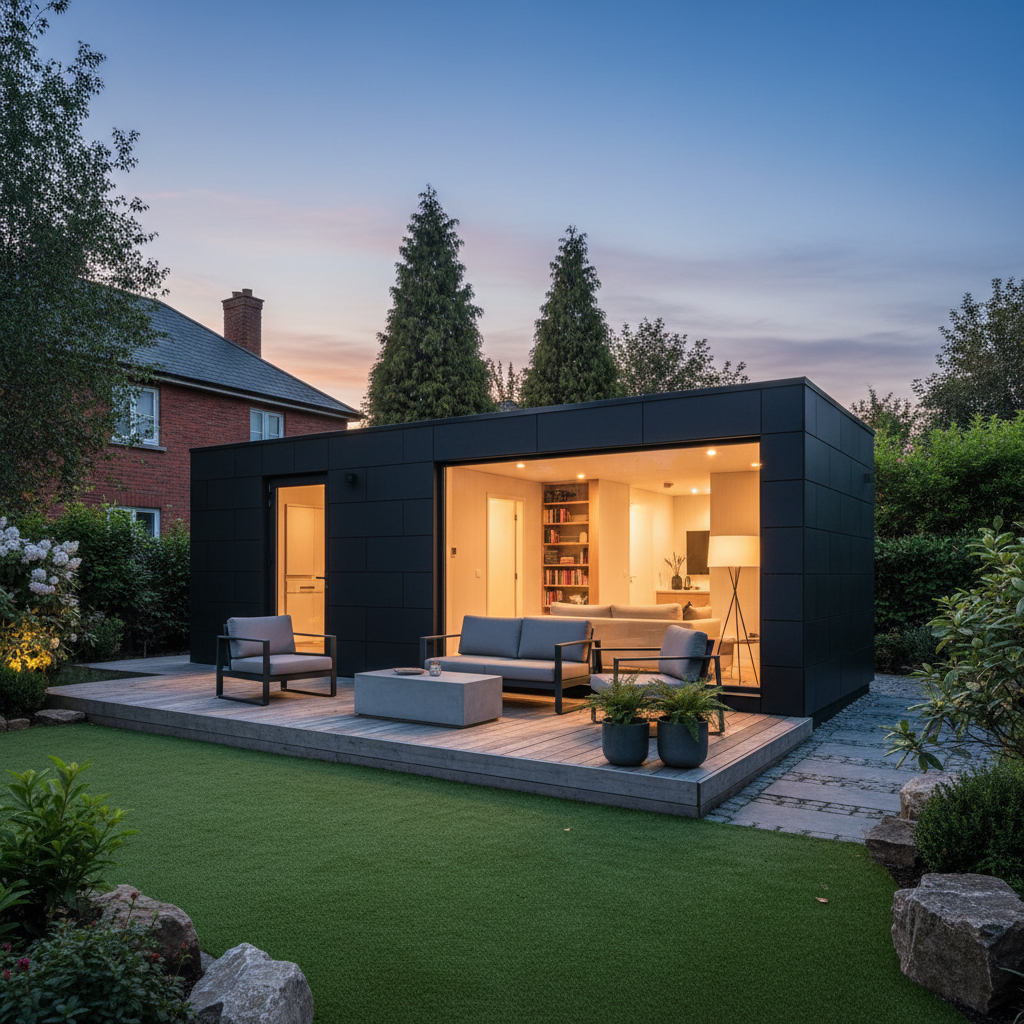
Looking for the full picture? Read our complete guide to modular homes in Ireland.
Financing a Modular Home in Ireland: What Banks Look For
Yes, you can get a mortgage for a modular home in Ireland — but banks look for specific things before they'll lend. This guide explains exactly what Irish banks look for when financing a modular home, and how to make your build lender-ready.
Can You Get a Mortgage for a Modular Home?
Yes. Certified modular and panel homes that meet Building Regulations are permanent with mainstream Irish lenders. The idea that modular homes aren't permanent is outdated — thousands of buyers finance them every year.
See our full mortgage guide: Can You Get a Mortgage on a Modular Home?
What Banks Look For
1. Certification
The home must be CE-marked and Building-Regulations-compliant. Banks won't lend on uncertified units, log cabins sold as homes, or temporary structures.
2. A Fixed, Written Contract
Lenders want a clear build contract with a fixed price and timeline. Variable or vague quotes make lenders nervous.
3. Planning Permission
A permanent modular home on its own site needs full planning permission. The bank will want to see it.
4. A Permanent Foundation
The home must be fixed to a permanent foundation — concrete pad, slab or an engineered ground-screw system. A home sitting on temporary blocks won't qualify.
5. Stage Payments
Mortgages on modular builds are typically drawn down in stages — deposit, manufacture, delivery, completion. The bank wants the milestones in writing so funds can be released cleanly.
6. A BER Certificate
A Building Energy Rating is required before the final drawdown. An A-rated home can also unlock green mortgage rates.
7. A Warranty
A structural warranty (e.g. Premier Guarantee, HAPM) strengthens your application and is required by some lenders.
How to Make Your Build Lender-Ready
- Use a reputable, certified manufacturer — lenders know the established names.
- Get planning permission early — it's non-negotiable for a mortgage.
- Insist on a fixed-price contract — with stage milestones in writing.
- Confirm the warranty — a structural warranty helps.
- Get mortgage approval in principle before you commit — so you know the budget.
- Ask about green mortgages — A-rated homes can get lower rates.
What If You're Adding a Pod or Granny Flat?
For smaller modular builds — a garden pod or granny flat — you usually won't need a new mortgage. Buyers typically use a mortgage top-up, a personal loan, a green home loan, or credit-union lending.
Talk to Us About Financing Your Build
At New Chapter Homes, every home we build is finance-ready — certified, contracted and supported through the drawdown process. Book a free consultation to talk through financing your modular build.
Explore Our Modular Homes
Related Articles
Granny Flats Ireland: Costs, Planning & Rental Income Guide
A practical Irish guide to granny flats and modular granny flats — what they cost, how planning permission works, the realistic rental income potential, energy efficiency and turnkey modular construction from New Chapter Homes.

Outdoor Kitchen Modules & Components: Building Your Garden Kitchen in Ireland
Modular outdoor kitchens let you build the exact layout you want. We break down the core modules and components — from cabinetry and fridges to grills and pizza ovens — and how to configure them for an Irish garden.
How Much Does an Outdoor Kitchen Cost in Ireland? 2026 Pricing Guide
What does an outdoor kitchen cost in Ireland? From a compact BBQ island to a full entertaining suite with pergola, we break down the pricing factors and what to expect in 2026.
Ready to Start?
Talk to Our Team Today
Get expert advice, a free consultation, and a tailored quote for your project.
Get in Touch